Floodwater leaves a line on the walls that no amount of scrubbing will hide. After a storm, owners across Texas wake up to soaked carpet, warped cabinets and a house that smells different than it did the day before. Plenty of owners want to rebuild. Others want out as fast as possible. This guide covers both paths, from the first photos for your insurance claim to the day you hand over the keys on a flooded house.
First Steps After a Flood in Your Texas Home
Safety comes before anything else. Stay out until local officials say the area is clear, and have the power shut off at the meter before anyone walks through standing water. Electrical systems, gas lines and weakened floors can all hide damage.
Once it’s safe, take pictures before you move a single thing. Get every room, the waterline on the walls, ruined appliances and the outside of the house. Those photos matter for your claim and for any buyer who later looks at your flooded house.
Call your insurance agent or carrier right away to report the loss. Ask for the claim number and the adjuster’s contact details, and write them down somewhere you won’t lose them.
Then start drying. Open windows when the air outside is drier than inside, run fans and dehumidifiers, and pull out wet carpet and padding. Speed matters more than perfection in the first two days.
Wear boots, gloves and a mask when you go back in. Floodwater can carry sewage and chemicals, and anything it touched should be treated as contaminated until it’s cleaned or thrown out.
Texas storms can bring wind and roof damage along with rising water, and those usually fall under a different policy than the flood itself. Keep the two claims separate in your notes.
Neighbors trade contractor names after every storm. Check licenses and reviews before you sign anything, and never pay the full price up front.
Keep every receipt from this stage. Pumps, fans, hotel nights and cleanup supplies may all matter later, whether you rebuild or sell.
Families displaced by a large Texas flood can ask local emergency management about shelter and assistance. A flooded house is hard enough without trying to live inside it.
How to Document Flood Damage for an Insurance Claim
Adjusters want to see the house as it was, not as it looked after cleanup. FEMA’s guidance on filing a flood insurance claim tells policyholders to photograph damaged property and water levels before throwing anything out.
Make a list of damaged contents as you go. Note what each item is, roughly when you bought it and what it cost, and keep any receipts or bank records that back it up.
Certain items have to go quickly for health reasons. Spoiled food, soaked mattresses and wet drywall can’t sit for weeks, so photograph them, cut a sample if your adjuster asks, and then remove them.
Video helps too. A slow walk through every room, narrated as you go, captures details that still photos miss, like water stains inside closets and swollen door frames.
Write down when the water came in and when it went down. Adjusters ask, and a buyer of a flooded house in Texas will want the same timeline.
Store copies in more than one place. Email the files to yourself, save them to cloud storage and keep a thumb drive with someone outside the flood area.
Your claim file doubles as your sales packet. A buyer looking at a flooded house in Texas wants to know what happened, what was removed and what was repaired.
How Flood Insurance Claims Work in Texas
Most policies here are written through the federal NFIP and sold by private carriers. Standard homeowners policies generally don’t cover rising floodwater, so check which policy applies before you assume anything.
Deadlines come fast. FEMA requires a signed proof of loss within 60 days of the flood for most claims, and a missing one can sink the claim. Your adjuster may help prepare it, but the responsibility stays with you.
Disputes have their own clock. Texas Law Help explains that a lawsuit over a denied flood claim goes to federal court and must be filed within one year. Talk to a lawyer well before that date if the numbers don’t add up.
Adjusters try to visit soon after a storm, though backlogs can stretch that after a widespread Texas flood. Be there for the inspection if you can, and walk the adjuster through every room of the flooded house, including the attic and crawlspace.
Found more damage after the first payment? You can usually file a supplemental claim, so keep documenting anything new, like a buckled subfloor that shows up weeks later.
Put every call in writing by sending the adjuster a short email that sums up what was said and what happens next.
Your mortgage lender may be named on the claim check. That’s common on homes with a loan, and it means the lender gets a say in how repair money is released.
What Flood Insurance Covers and What It Doesn’t
Policy limits shape every decision about a flooded house. According to United Policyholders, an NFIP policy covers up to $250,000 for the building and up to $100,000 for a home’s contents.
Building coverage pays for the structure and its systems. Think walls, floors, the electrical panel, the water heater and built-in cabinets.
Contents coverage is separate and has to be bought on its own line. Plenty of owners discover after a storm that they only bought building coverage.
Living expenses are a gap. The same Texas Law Help article notes that NFIP policies don’t pay for additional living costs, so hotel stays and rent while you’re displaced usually come out of pocket.
Basements and crawlspaces get limited coverage too. Finished areas below grade often aren’t covered the way the main floor is.
Upgrades get capped too. Insurance pays to restore what was there, so a flooded house with dated finishes won’t get enough to come back better than before.
NFIP policies list deductibles for building and contents separately. Check both before you estimate what the claim on your flooded house will pay.
Read your declarations page before you make any big choice. Knowing what the claim will pay is the first step toward deciding whether to rebuild or sell.
How Fast Mold Starts in a Flooded House
Mold doesn’t wait for paperwork.
The EPA’s guide to mold and moisture says wet materials should be dried within 24 to 48 hours to prevent growth. Two days pass quickly when you’re also finding a hotel and calling an adjuster.
Heat and humidity in Texas make that window tight. Drywall, insulation and carpet padding hold water long after the floor looks dry, and mold can grow behind walls where nobody sees it.
Indoor humidity is the number to watch. The EPA recommends keeping it below 60%, and ideally between 30% and 50%, which usually means running dehumidifiers for days.
Cut out wet drywall above the waterline. Many crews remove a band above the visible line, because water wicks upward into the wall.
Bleach isn’t a cure-all. Soaked porous materials like drywall, insulation and carpet padding usually need to come out rather than be wiped down.
Mold also changes the conversation with buyers of a flooded house. Many will ask for a clearance report, and a missing one can sink a financed sale in Texas.
Large mold problems call for a professional. Hire a qualified remediation company, ask how they’ll contain the work, and keep their report for the buyer.
Plenty of owners stop here. Once the walls are open and the mold estimate is in, a flooded house can look less like a repair project and more like a reason to sell.
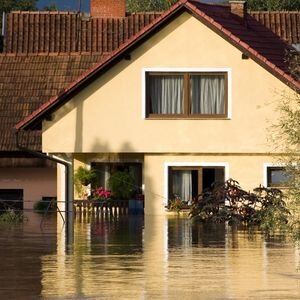
Should You Repair or Sell a Flooded House As-Is?
Start with three numbers: what the claim will pay, what the repairs will cost and what the house will be worth when it’s done. If the gap between repair costs and the claim is bigger than you can cover, selling starts to make sense.
Get written estimates from licensed contractors, not just a ballpark from a friend. Ask each one to separate flood repairs from other work, so you’re comparing like with like.
Time is part of the cost. Rebuilding after a widespread flood can drag on for months, because contractors and materials get booked up across whole regions of Texas.
Your mortgage, insurance, utilities and property taxes keep coming due through all of it, even while you’re paying rent somewhere else.
Emotional cost counts as well. One family wants the house they raised kids in back the way it was, and the next never wants to sleep in that flooded house again.
Floodplain rules can surprise you. Cities in Texas that take part in the NFIP can require a badly damaged home in a floodplain to meet current floodplain rules. That can mean raising the house. Ask your city’s floodplain office whether your flooded house crosses that threshold before you sign a rebuild contract.
What happens if you start repairs and then decide to sell? You can still sell mid-project, but buyers will price in the unfinished work, so think it through before you open every wall.
Owners who choose to sell as-is skip the rebuild entirely. Our guide to selling a house with water damage in Texas goes deeper on that choice.
What Texas Sellers Must Disclose About Flooding
Honesty protects you. Texas Property Code Section 5.008 sets out the seller’s disclosure notice for most home sales, and it asks specific flood questions.
The notice covers whether the home has flood insurance and whether water has entered the structure because of a natural flood event. It also asks about floodplain, floodway, flood pool and reservoir locations.
Repairs don’t erase history.
A flooded house that’s been fully rebuilt still flooded, and a buyer is entitled to know that when the form asks. Mold history belongs in the conversation too, so share any remediation report and clearance testing.
Buyers in Texas can pull up FEMA flood maps on their own, so a floodplain location is hard to hide anyway.
Fill out the form yourself, carefully, even if a Texas agent hands it to you. Your signature goes on it, and the answers are yours.
Keep your answers factual. Attach the remediation report, the contractor invoices and the photos so the buyer can see what was done.
Buyers who find out later tend to call lawyers. Telling them up front costs you far less than defending a claim after closing.
Selling as-is doesn’t change your duty to disclose what you know. Our post on selling a house as-is without an inspection in Texas explains how those rules fit together.
How Flood Damage Changes the Price of a Texas Home
Buyers won’t use the neighborhood average for a gutted house. They start with what the house would be worth repaired, subtract the repair costs, and then subtract more for risk and time.
Comparable sales are thin. Few flooded houses sell in any one neighborhood, so appraisers and buyers have less to go on than they would for a move-in-ready home.
Market conditions add pressure. Texas REALTORS reported a statewide median sales price of $333,628 in the third quarter of 2026, with months of inventory at 5.5. With that many homes to choose from, buyers have little reason to stretch for one that needs a full gut.
Time on market has grown as well. Realtor.com figures published by the St. Louis Fed show the median Texas listing at 68 days on market in October 2026. A flooded house with open walls usually sits longer than that.
Within a city, one street can price very differently from the next. A home on a street that floods often will price lower than one that flooded once in a historic storm, even with identical damage.
Ask any buyer to walk you through their math on your flooded house. A buyer who won’t explain the number deserves a careful second look.
Storm season plays a part as well. Flood risk sits at the front of buyers’ minds in Texas after a big storm. A flooded house listed right then competes with every other damaged home in the area.
Your documentation can lift the price. Clear photos, adjuster reports and contractor estimates take guesswork out of a buyer’s math, and less guesswork usually means a better offer.
Why Financed Buyers Struggle With Flood-Damaged Homes
Nearly every retail shopper needs a mortgage. Lenders want a home that’s safe and livable before they’ll lend on it, so a gutted kitchen or missing drywall can stop a loan in its tracks.
Appraisals add another hurdle. An appraiser may value the home well below the contract price, or call for repairs before closing that the seller can’t afford.
Flood insurance comes up too. A buyer in a high-risk flood zone with a federally backed mortgage will usually need a flood policy, and the quote can change the buyer’s monthly payment.
Inspections uncover more. A buyer’s inspector may find moisture readings, mold or electrical damage that sends the buyer back to renegotiate or walk away.
Renovation loans exist, but they add paperwork, contractor bids and inspections, and plenty of sellers of a flooded house in Texas can’t wait on them.
That’s why many owners of a flooded house in Texas end up selling for cash. A cash buyer doesn’t need a lender’s approval, an appraisal or a livable kitchen to close.
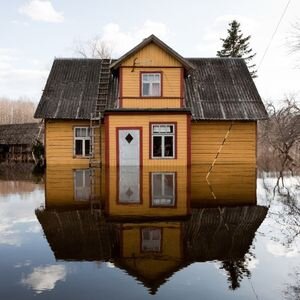
Title, Liens and Paperwork Before a Texas Closing
Buyers and title companies care about clean title as much as the house itself. Unpaid contractors can file mechanic’s liens, and missed HOA dues or property taxes during a displacement can turn into liens too.
Order a title search early. Your title company will spot liens and judgments before they hold up the closing, and you’ll have time to pay or negotiate them.
Insurance money needs a plan as well. If you sell before the claim is settled, talk with your insurer and your lender about who receives the remaining payments.
Property tax relief may be available after a disaster. Ask your county appraisal district whether any exemption or reappraisal applies to damaged homes in your area, and keep the answer in writing.
Cities sometimes red-tag severely damaged homes. If yours has been condemned, our page on the requirements for a condemned house in Texas covers the extra steps.
Contractor deposits deserve a look. If you paid a crew that never finished, ask the title company whether anything was filed against the flooded house before you list it.
Probate adds a step if the owner passed away after the flood. Heirs or the executor will need authority to sign before a title company will close on the flooded house.
Gather the deed, the survey, your insurance policy and your mortgage statement in one folder. Having them ready can cut days off a Texas closing.
How to Sell a Flooded House Fast in Texas
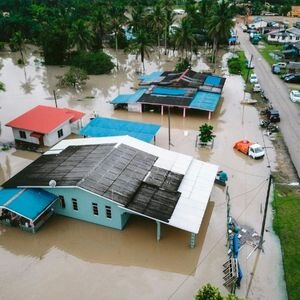
Speed comes from fewer moving parts. No lender, no appraisal, no repair requests and no showings to a stream of buyers who walk in, smell the drywall and leave.
Cash buyers price the damage in and close as the house sits. At House Buying Girls, we buy flood-damaged homes as-is, and you can leave behind anything you don’t want to keep.
Our process is simple. You call or fill out the form, we look at the house and your documentation, and we make a written cash offer. Then the closing date is yours to pick.
Belongings or tenants still inside don’t have to stop the sale. Tell the buyer up front, and agree on what stays, what goes and when the flooded house will be empty.
Bring your claim file to the walkthrough. A buyer who sees the photos, the adjuster’s estimate and the remediation report can price your flooded house with more confidence.
Owners west of Dallas can start with our page for we buy houses in Fort Worth, TX. Talking to more than one of the cash home buyers in Texas is smart, and House Buying Girls will explain exactly how we arrived at our number.
One Monday I walked a flooded house in Arlington where the owner had already pulled out the carpet and stacked the wet drywall in the garage. She’d been paying rent across town for three months. We closed on her timeline, and she never had to choose a single paint color.
Another time, in Farmers Branch, a widower called us after a burst supply line upstairs ran for a full weekend while he was away. The ceiling in the dining room had come down onto the table. He sold to us as-is and moved closer to his daughter.
Neither of them had to finish the repairs, wait on a lender or field showings.
Cash sales give up a little price in exchange for certainty and speed.
Flooded House Questions Texas Owners Ask
Can I Sell a Flooded House Before the Insurance Claim Is Settled?
Usually, yes. Tell the buyer about the open claim, and ask your insurer and lender how any remaining payments will be handled after the sale. Get that agreement in writing before closing.
Do I Have to Tell Buyers About a Flood if the House Was Repaired?
Yes, if the disclosure form asks and you know the answer. A full repair doesn’t change the fact that water entered the home, and buyers can ask for your repair records.
Will a Cash Buyer Pay Less for a Flooded House?
Cash offers reflect the cost of repairs, the time to complete them and the risk the buyer takes on. In return, you skip the repair bills, commissions and months of holding costs, so compare what you’d net both ways.
Can I Sell a Flooded House in Texas Without Fixing Anything?
Yes. Cash buyers and investors buy homes with open walls, missing floors and active claims. You still owe buyers an honest disclosure, but you don’t owe them a repair.
Is It Hard to Sell a Home in a Flood Zone in Texas?
It can be. Buyers with loans may need flood insurance, which raises their monthly cost, and some buyers simply won’t consider a floodplain. A clear history and good records help, and cash buyers don’t face the same loan rules.
If floodwater has you ready to move on, contact House Buying Girls or call (214) 393-8026 today. We’ll look at your house, walk you through your options and make a fair cash offer with no repairs needed.
Helpful Texas Blog Articles
- Selling A Mold-Affected House In Texas
- Texas Earnest Money Rules
- How Much Do You Lose Selling a House As-Is in Texas
- How to Sell a Hoarder House in Texas
- Can You Sell a House for Less Than You Owe in Texas?
- How to Sell Your House With a Lien in Texas
- How to Sell Your Fire-Damaged House in Texas
- Selling Parents’ House After Death in Texas
- Texas Realtor Commission Rates For Selling Your Home
- What Do I Have To Disclose When Selling A House in Texas
- Can A Buyer Back Out After Inspection in Texas
- Sell A House With A Reverse Mortgage In Texas
- Sell Your Flooded House Fast In Texas